- Properties
- Develop a Resort
- Buy a Hotel or Resort
- Land for Resorts
- Compare Investments
- ROI Calculator
- NRI Calculator
- Blog
- Research & Reports
- Trust Center
- Press
- Contact
- FAQ
- Leadership
Speak to an Advisor
+91 98290 17524
Buy a registered unit inside a branded resort. Earn 8–9% assured rent for five years, then a 50% share of net resort profit. Pay no daily attention to operations. Independent advisor across Marriott, Hyatt, Wyndham & Indian Hotels.
Resort investment in India today means one of three structurally different things — and most generic guides confuse them.
Sale-leaseback unit ownership is the dominant model. You buy a specific identified unit inside a branded resort. The sale deed is in your name. You simultaneously sign a registered Sale-Leaseback agreement leasing the unit back to the developer or operator. The operator runs the hotel; you receive a fixed, location-based assured rent of 8–9% a year for the first five years — paid quarterly, regardless of occupancy — after which income becomes a 50% share of the resort's net profit, variable and with no minimum.
Fractional ownership is the lower-ticket alternative — you own a share in an SPV that owns the unit, with performance-linked returns from day one rather than a five-year assured rent. Direct hotel ownership is the institutional route — ₹15 crore+, full operating risk.
ResortWealth is built around sale-leaseback specifically because it offers registered title + five-year assured rent + RERA compliance in a single instrument. The detailed comparison is in our sale-leaseback vs fractional guide.
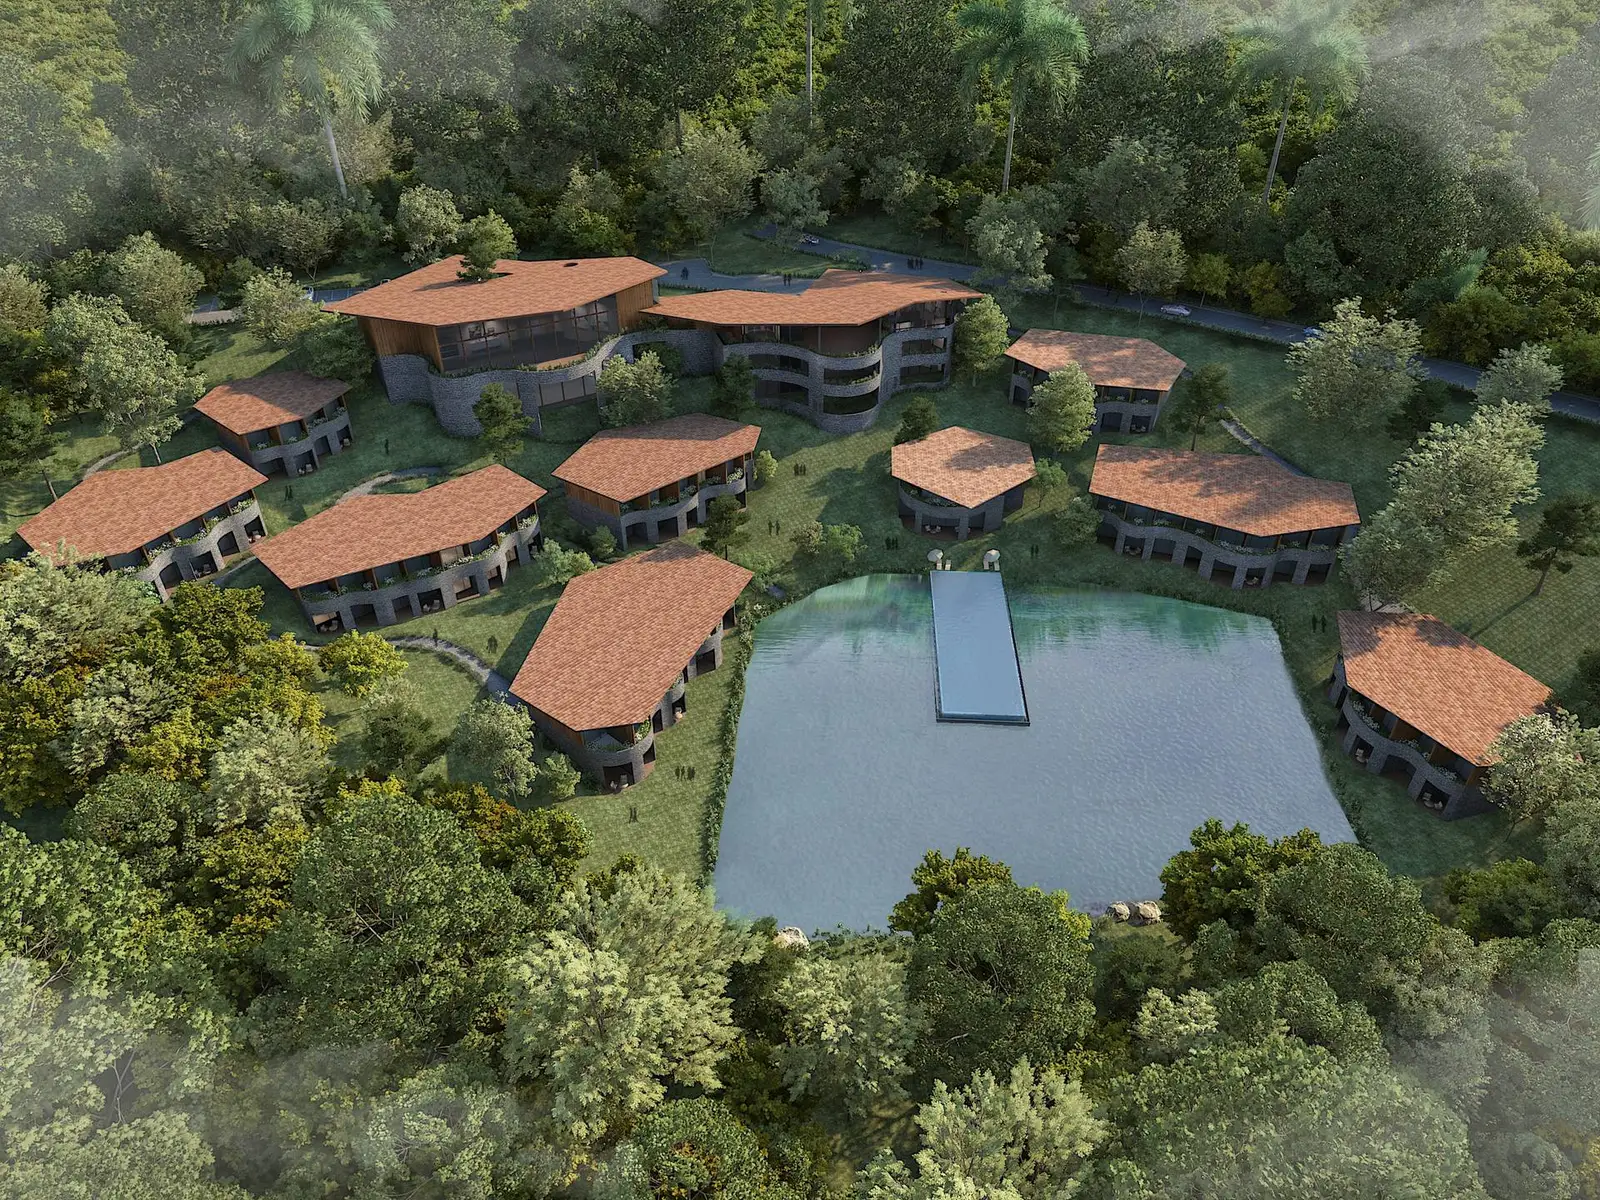
Curated branded resort opportunities across India — Marriott, Hyatt, Wyndham, Indian Hotels.
| Route | Entry ticket | Return | Best for |
|---|---|---|---|
| Direct ownership | ₹15 cr+ | 12–20% IRR | Family offices |
| Sale-leaseback unit | ₹40 L+ | 8–9% for 5 yrs, then profit share | HNI / NRI income |
| Fractional ownership | ₹10 L+ | 8–14% expected | Mid-market entry |
| SM REIT / Listed REIT | ₹10 k+ | 6–9% yield | Liquid retail |
| Listed hotel stocks | Any | Equity-linked | Sector exposure |
| Hospitality AIF | ₹1 cr+ | 15–22% IRR | Sophisticated HNI |
Full route-by-route breakdown: Hotel Investment India — 6 Routes Compared.
Sale-leaseback rent is classified as Income from House Property — triggering the 30% standard deduction under Section 24(a).
For a financed investor, post-tax effective yield can exceed the gross yield in early years. For an unfinanced investor, post-tax yield typically lands at 6.5–7.5% during the five assured years.
Read the full tax breakdown →NRIs and OCIs can buy registered branded resort units freely under FEMA general permission. No prior RBI approval. Restrictions apply only to agricultural land, plantation property, and farmhouses.
For US-based NRIs specifically, sale-leaseback is one of the cleanest non-PFIC routes available — direct real-estate ownership sits outside the PFIC regime that taxes Indian mutual funds heavily.
FEMA framework for NRI investment →Each market has a distinct ticket size, occupancy profile, and appreciation curve.
Destination comparison: Goa vs Coorg vs Sakleshpur.
Resort investment in India typically means buying a registered unit (room, suite, or villa) inside a branded resort and leasing it back to the operator under a Sale-Leaseback agreement. You receive a fixed, location-based assured return of 8–9% a year for the first five years, after which income becomes a 50% share of the resort's net profit — variable, with no minimum — plus 15–25 free stay nights per year, with the option to sell or transfer your title at any time.
Branded resort sale-leaseback units in mid-market brands (Wyndham, Ramada, Lemon Tree mid-segment) start at ₹40 lakh. Premium brands (Marriott, Hyatt) begin at ₹1.5 crore+. Fractional ownership in branded hospitality starts at ₹10 lakh. SM REITs are accessible from ₹10,000.
A resort sale-leaseback gives you registered ownership of a specific physical unit with rent that is contractual for the first five years and profit-linked thereafter. A REIT gives you a unit of a listed entity that pools many properties — fully liquid but market-priced. Resort SLB yields are typically 8–9% assured for five years, then a 50% share of net resort profit (no floor); REIT distributions 6–9% market-linked.
Yes. NRIs and OCIs can buy commercial and residential immovable property in India freely under FEMA general permission, including branded resort units. Restrictions apply only to agricultural land, plantation property, and farmhouses.
An assured rental yield of 8–9% a year for the first five years, then a 50% share of net resort profit (variable, no floor), plus historical capital appreciation of 5–8% CAGR for branded hotel real estate in good locations. The five-year assured rent is a covenant, not a lifetime one; from year six model your income as an equity-style share of resort profit.
Rental income is classified as Income from House Property and taxed at slab rates after the 30% standard deduction under Section 24(a). Long-term capital gains on sale (held >24 months) are taxed at 12.5% without indexation.
Mature markets like Goa offer proven yield and exit liquidity. Established growth markets like Coorg balance ticket size and appreciation. Emerging destinations like Sakleshpur, Jawai, and Chikmagalur offer the highest forward upside with longer occupancy ramps.
No — a branded resort unit is a commercial hospitality asset, not a residential home, so standard bank home loans do not apply, and ResortWealth does not arrange loans. Investors buy outright or in stages through the developer's construction-linked payment plan.
Not as a standalone product. As of 2026 every listed Indian REIT is built around offices, retail or warehousing; hotels appear only as minority parts of some of those portfolios, and no hospitality-only REIT has listed. Listed hotel companies such as IHCL, EIH, Chalet, Lemon Tree, Juniper, SAMHI and Ventive are ordinary shares, not REITs. If you want income from a specific hotel or resort, the practical routes are a sale-leaseback unit (registered title and contractual rent for five years), a fractional or SM REIT scheme that happens to hold a hotel, or those listed hotel shares.
Five steps. 1) Decide what the money is for — fixed income for five years, personal stays, or long-term growth — and fix your ticket. 2) Shortlist branded projects where the rent is written into a registered lease, and check RERA registration where it applies. 3) Verify the paying entity, the title, the escrow arrangement and the terms after year five, in writing. 4) Sign, pay by bank transfer (outright or through the developer's construction-linked plan — these units are not loan-eligible), and register both the sale deed and the lease at the sub-registrar. 5) Rent starts on the date the lease states and is paid on its schedule, with TDS deducted at source. Your first consultation with ResortWealth is free.
Tell us your goal — income, growth, retirement, or NRI India exposure — and we will share property-specific projections with real lease terms and RERA documents. Independent advisory. No obligation.